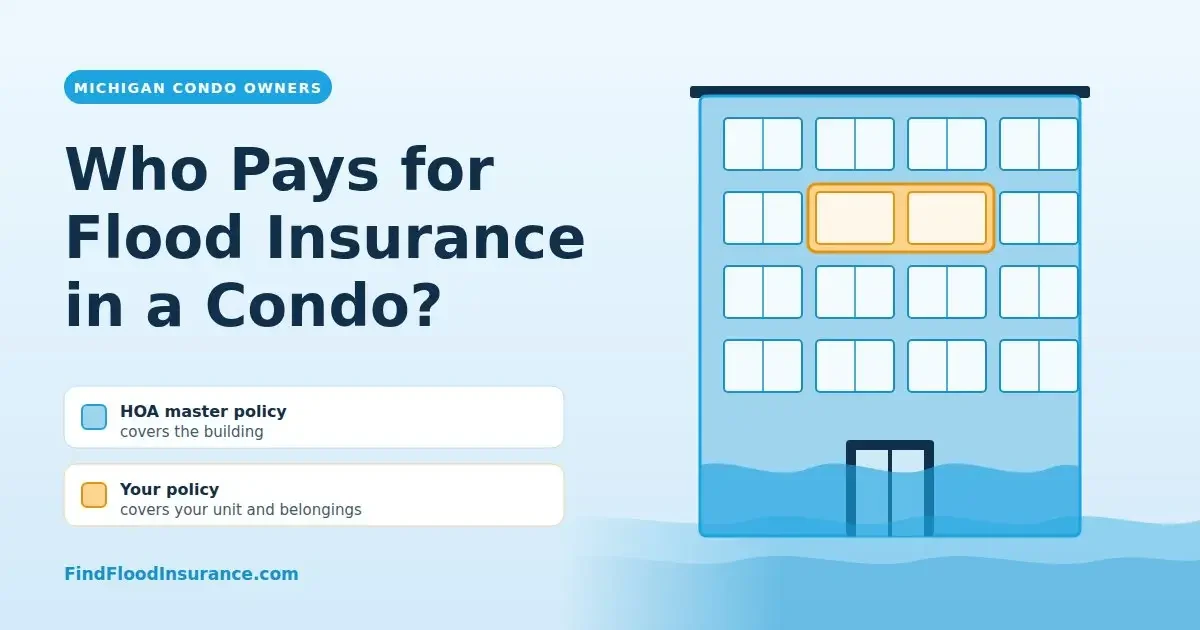
The short answer: your condo association buys the master flood policy for the building and pays for it with HOA dues. You buy your own policy for what the master policy doesn’t cover, which is mainly your belongings and, in many cases, extra building coverage for your unit and coverage for special assessments. These are two separate policies. Neither one replaces the other.
If you own a condo in Michigan, flood insurance can fall between two sets of responsibilities. The association handles the building, you handle your unit, and a flood doesn’t respect that line. This guide explains who pays for what, what each policy covers, when a mortgage lender gets involved, and the questions to ask before you buy.
Last reviewed: October 2026. Coverage limits and program rules change, so confirm current figures with your agent.
Who pays for what in a condo flood claim
| What was damaged | Who usually pays | Which policy |
|---|---|---|
| The building structure and common areas (foundation, lobby, hallways, elevators, shared mechanical systems) | The HOA, through your dues | The association’s master flood policy |
| Walls, floors, cabinets, and built-ins inside your unit | Depends on how the master policy is written. You can add your own building coverage to fill gaps | Master policy, plus your own policy if needed |
| Your furniture, electronics, clothing, and belongings | You | Your own flood policy (contents coverage) |
| A special assessment the HOA charges owners after a flood | You, unless your policy includes loss assessment coverage | Your own flood policy |
| The association’s own deductible | The owners, as an assessment | Not covered by your loss assessment coverage |
The most common mistake is assuming the HOA’s policy protects everything inside your four walls. It usually doesn’t.
What the HOA’s master flood policy covers
Most condo associations that buy flood insurance through the National Flood Insurance Program (NFIP) use a Residential Condominium Building Association Policy, or RCBAP. Associations can also buy private flood coverage designed to work the same way.
According to FEMA’s guide for condominium associations, an RCBAP:
- Insures the building against direct physical damage from a flood.
- Can pay up to $250,000 in building loss payments for any one unit.
- Covers common property such as the foundation and foundation walls, building structure, electrical systems including elevators, staircases, central air conditioning, furnaces, heat pumps, and water heaters.
- Can include optional contents coverage for items the association owns in common, like lobby furniture and maintenance equipment.
Associations can buy the policy at any time, but it can carry a 30-day waiting period before it takes effect. The premium is typically paid by the association as a common expense, which means it comes out of your dues.
What an RCBAP does not do, according to FEMA, is protect your personal belongings. FEMA tells associations to encourage unit owners to buy their own contents or building coverage.
Ask your board for the policy’s declarations page. It shows the coverage amount, the deductible, whether the building is insured at full replacement cost, and what the policy treats as part of your unit. If the board can’t produce it, that is worth knowing before a flood, not after.
What you need to buy yourself as a unit owner
A homeowners-style condo policy (often called an HO-6) typically excludes flood. For more on that gap, see our guide on whether homeowners insurance covers flooding in Michigan. A separate flood policy can fill three gaps:
1. Contents coverage. This covers your furniture, appliances that aren’t part of the building, electronics, clothing, and other belongings. It’s the one piece the master policy almost never provides.
2. Building coverage for your unit. If the master policy is written for less than full replacement cost, or doesn’t treat interior finishes as part of the building, your own building coverage can pay for the difference inside your unit.
3. Loss assessment coverage. If the association levies a special assessment after a flood to repair damage to the unit or common areas, FEMA explains that the NFIP policy can pay your share up to the building coverage limit on your policy. It does not cover an assessment that results from the association’s own deductible, and you must submit a sworn proof of loss with documentation of the assessment. Our guide to filing a flood insurance claim in Michigan walks through that process.
For a standard NFIP policy on a residential unit, building coverage tops out at $250,000 and contents coverage at $100,000. Some private flood policies offer higher limits, which we compare in NFIP vs. private flood insurance in Michigan.
When your mortgage lender requires condo flood insurance
If your unit is in an attached building in a FEMA Special Flood Hazard Area (zones that begin with A or V, such as Zone AE) and your loan is backed by Fannie Mae, the lender has to verify the association carries the required master flood coverage. Fannie Mae’s Selling Guide sets the building coverage minimum at the lesser of 80% of the replacement cost or the maximum NFIP coverage available per unit.
If the master policy falls short, you may be required to buy a supplemental policy for the difference. Other lenders and loan programs have their own rules, so ask yours early. If you’re in the middle of a purchase, read flood insurance and home closing in Michigan before closing, and note that a new policy usually has a waiting period.
What condo flood insurance costs in Michigan
There’s no single price. Your premium depends on:
- The flood risk of the building and its location
- Which floor your unit is on, and whether there is a basement or garden level
- Your building and contents coverage amounts
- Your deductible
The association’s premium is shared among all owners through dues, so a building in a higher-risk area tends to show up in your monthly fees even if you never buy your own policy. For a broader look at pricing trends, see why Michigan flood insurance costs went up. The fastest way to get a real number for your unit is a free quote.
Why Michigan condo owners should pay attention
Michigan condos sit along the Great Lakes shoreline, on river corridors, and in dense urban areas where heavy rain overwhelms drainage. The state’s Department of Environment, Great Lakes, and Energy publishes information on Great Lakes coastal flood hazard studies that shows how shoreline risk is being mapped.
A condo does not have to be in a mapped high-risk zone to flood. Read more in do you need flood insurance in Michigan if you’re not in a flood zone, and check your own address with the flood zone checker on our homepage or the Michigan flood zone map guide.
Flood risk varies a lot from one Michigan community to the next. Our Michigan service areas pages cover the local flood risks in each region.
Four steps for condo owners
- Get the master policy’s declarations page from your HOA or property manager.
- Check your flood zone with the free checker on our homepage.
- Compare the gaps. Note the deductible, the replacement cost basis, and what the master policy treats as your unit.
- Get a quote for contents, building, and loss assessment coverage, and compare NFIP and private options.
Frequently asked questions
Do condo owners need their own flood insurance?
Often, yes. The association’s master policy protects the building, not your belongings. If you want coverage for your contents, for gaps in the building coverage inside your unit, or for special assessments, you need your own policy. A lender may also require one.
Does the HOA’s flood insurance cover my personal belongings?
No. According to FEMA, the association’s policy covers the building and the association’s own property. Your furniture, electronics, and clothing need contents coverage on your own policy.
Who pays if the building floods and the HOA’s coverage isn’t enough?
The shortfall is usually passed to owners as a special assessment. Loss assessment coverage on your own flood policy can pay your share of an assessment for flood damage, up to your policy’s limit, but not an assessment caused by the association’s own deductible.
Does my HO-6 condo policy cover flood damage?
Typically not. Standard HO-6 policies exclude flood. That is why a separate flood policy matters. Check your policy for sewer or drain backup coverage, which is a different thing and is usually an endorsement.
Can I buy private flood insurance for a condo?
Often, yes, though some lenders and condo associations have requirements about which policies they accept. Ask your lender and your board before you buy.
How long before my condo flood policy starts?
NFIP policies typically have a 30-day waiting period, with some exceptions such as a policy bought in connection with a loan closing. Buy before you need it, not when a storm is in the forecast.
Get a condo flood insurance quote
We’re a Michigan agency that only sells flood insurance, so we spend our day on questions like these. Request a free flood insurance quote and we’ll look at your building, your master policy, and the gaps.
Want to keep learning? Browse the rest of the Michigan Flood Insurance Learning Center.
If your condo association is the one asking questions, our guide to flood insurance for condo associations covers the HOA’s side.
Sources and further reading
- FEMA: Flood Insurance for Condominium Associations (RCBAP brochure)
- FEMA FloodSmart: Condo loss assessment claims
- Fannie Mae Selling Guide B7-3-06: Flood Insurance Requirements for All Property Types
- FEMA: Dwelling Form Standard Flood Insurance Policy
- Michigan EGLE: Great Lakes Coastal Flood Hazard Studies
- FEMA Flood Map Service Center